
Blog
Should I Finance a Mattress How to Decide Smartly

A homeowner in Dyer or Crown Point often reaches the same uncomfortable moment: the mattress has lost its support, sleep has become restless, and replacing it feels like a larger purchase than the household budget expected. The question, “Should I finance a mattress?” deserves more than a quick look at the monthly payment. It's a decision about sleep wellness, total cost, cash flow, and the risk of missing a payoff deadline.
For families in St. John, Schererville, Munster, and throughout Northwest Indiana, Groen's Fine Furniture has provided personal guidance since 1983. The family-owned team understands that a mattress affects more than a bedroom. It can influence rest, comfort, and how well a household manages its financial commitments. Shoppers can begin with this local mattress shopping resource and then test comfort in person instead of choosing based only on an online payment headline.
The right answer is direct. Financing can make sense when the mattress is needed, the promotion is understood, and the balance can be cleared before expensive terms begin. Paying cash, saving first, or choosing a shorter-term option can be wiser when the required payment would feel tight. The sections below focus on the trade-offs, a practical affordability test, offer fine print, alternatives, and a comfortable next step with a local team.
Introduction for Northwest Indiana Shoppers Weighing Mattress Financing
A worn mattress doesn't always fail dramatically. Sometimes it sags gradually, leaves a sleeper stiff in the morning, or no longer provides the support and pressure relief that made it comfortable in the first place. Sleep-health guidance commonly places mattress replacement at 6 to 8 years under normal conditions, though construction and use affect longevity, as explained by the Sleep Foundation's mattress replacement guidance.
That creates a familiar household decision. A Crown Point couple may know the mattress needs replacing but prefer to keep cash available for home repairs. A Dyer parent may need better support now but worry that financing turns a necessary purchase into lingering debt. Both concerns are reasonable. A mattress is a wellness purchase, but the payment still has to fit real life.
The question behind the monthly payment
The better question isn't whether a payment looks manageable. It's whether the buyer can repay the full balance within the promotional period without relying on a future bonus, a tax refund, or a credit card balance transfer. Financing may provide buying power, but it doesn't remove the obligation.
The Consumer Financial Protection Bureau emphasizes understanding the payment schedule, total cost, and consequences of missed payments before accepting credit terms, particularly when a promotional period is involved. That guidance supports a simple standard for Northwest Indiana shoppers: the offer should be clear before the mattress comes home.
Comfort and financial wellness belong together
A mattress that no longer supports the body can make each night harder. Guidance on mattress replacement connects the decision to functional wear, including lost support and comfort, rather than appearance alone, according to National Mattress Authority's replacement information. If the current bed has reached that point, delaying indefinitely may not serve the household.
Groen's multigenerational service in NWI is built around honest, benefit-focused guidance. The goal isn't to push a payment plan. It's to help a family choose lasting comfort, understand the cost, and decide whether financing fits without pressure.
Pros and Cons of Financing Your Next Mattress
A failing mattress can leave a household choosing between poorer sleep now and a large cash purchase later. Financing may solve the timing problem, but the monthly payment is only the starting point. The payoff window determines whether the offer remains affordable.
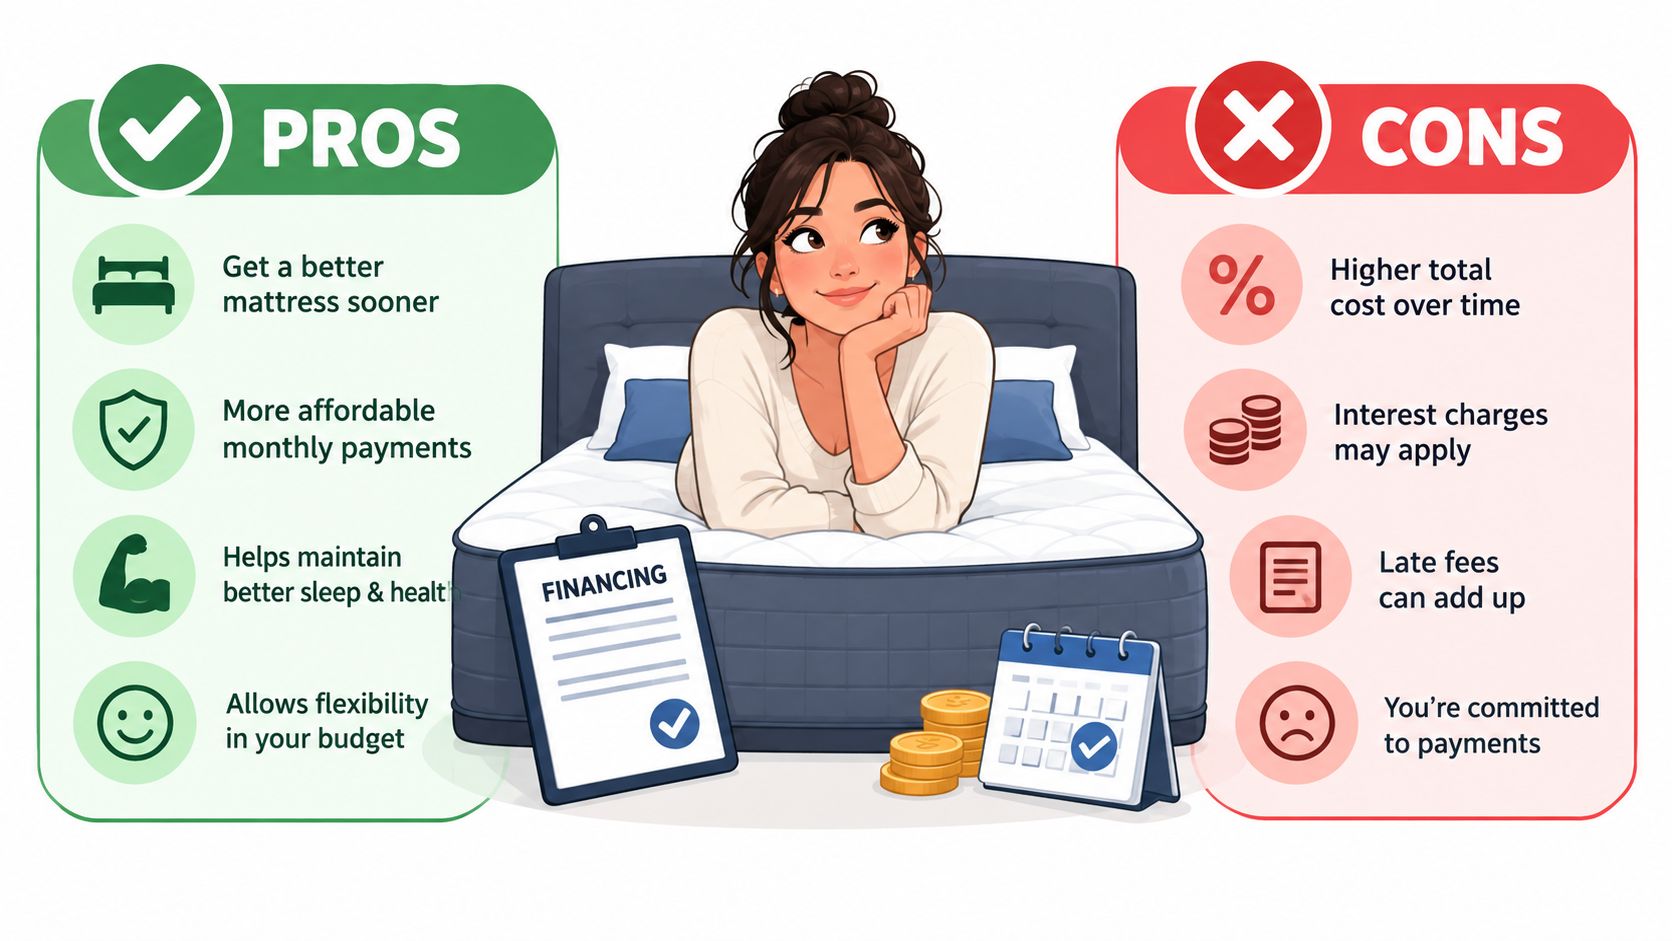
Financing can help replace a worn mattress without using all available cash at once. It may also let a shopper choose a more durable mattress with better support instead of settling for a lower-quality option based only on today's cash balance. That can make comfort and construction more accessible, provided the full balance can be cleared on schedule.
What financing can do well
A well-chosen plan can keep cash available for necessities while dividing a large purchase into predictable payments. It works best when income is stable, the payoff deadline is written down, and automatic payments are set high enough to clear the balance before the promotional period ends.
Buy now, pay later financing has become a familiar way to divide household purchases. Federal Reserve analysis reported that providers originated about $156.7 billion in consumer credit products in 2025, with approximately 63% carrying 0% APR and about 37% carrying APR charges. The Federal Reserve's BNPL analysis shows why shoppers must read the specific offer. Confirm whether it is interest-free, how payments are calculated, and what happens if the balance remains at the deadline.
Where the risk appears
Risk grows when a shopper judges the offer by its advertised payment alone. Deferred-interest terms may apply interest retroactively to the original balance if the payoff deadline is missed. Late fees and higher rates after the promotion can turn a convenient plan into an expensive balance.
Paying cash avoids financing charges and deadline risk, but it can leave less room for emergencies. Financing keeps cash available while creating a fixed obligation. Choose based on which risk your household can handle, not on the smallest payment shown in the advertisement.
The practical takeaway: Financing makes sense when the total cost is clear, the payoff window is realistic, and the mattress meets a genuine comfort need rather than an impulse.
Review Groen's mattress financing options with the team, then compare the required payoff amount with paying cash. The right choice should protect sleep quality and leave the household with enough financial breathing room.
How to Tell If Financing Fits Your Budget Right Now
A financing decision should survive a simple stress test. The buyer doesn't need complicated math, but the calculation must include the entire purchase and the deadline.
Start with the payoff amount
First, identify the total amount that must be repaid. Include the mattress, applicable tax, delivery, and any accessories. Then divide that amount by the number of months in the promotional period. The result is the payment required to clear the balance before the offer expires.
The table below shows the basic calculation using the total purchase amount. It doesn't include any possible taxes, delivery charges, accessories, fees, or lender-specific terms, so those items must be added to the calculation.
| Total Purchase Amount | 12 Month Promo | 24 Month Promo | 36 Month Promo |
|---|---|---|---|
| Total purchase amount | Total ÷ 12 | Total ÷ 24 | Total ÷ 36 |
A plan advertised at 0% still requires the buyer to make enough progress each month to reach a zero balance by the deadline. Minimum payments may not be sufficient.
Test the payment against the household
Next, compare the required payment with dependable monthly income after housing, utilities, food, transportation, insurance, existing debt, and regular savings. A payment that works only when overtime arrives or an unrelated bill stays unusually low is too tight.
Households carrying several obligations can use a resource such as calculate your debt ratio to understand how the proposed payment fits alongside existing debt. The calculation isn't a substitute for reading the financing contract, but it can expose a budget that already has little room.
Build protection into the plan
Autopay should be scheduled for more than the minimum whenever the promotion requires a full payoff by a specific date. A buyer should also retain emergency savings rather than committing every available dollar to the mattress. If the payment feels uncomfortable before signing, the honest answer is to select a lower total purchase amount, save longer, consider layaway, or wait.
Groen's offers Special Financing subject to credit approval, which can provide buying power for a quality mattress. Approval doesn't determine affordability. The household budget does. A confident yes means the payoff amount fits with room to handle ordinary surprises.
How to Compare Mattress Financing Offers Without Getting Trapped
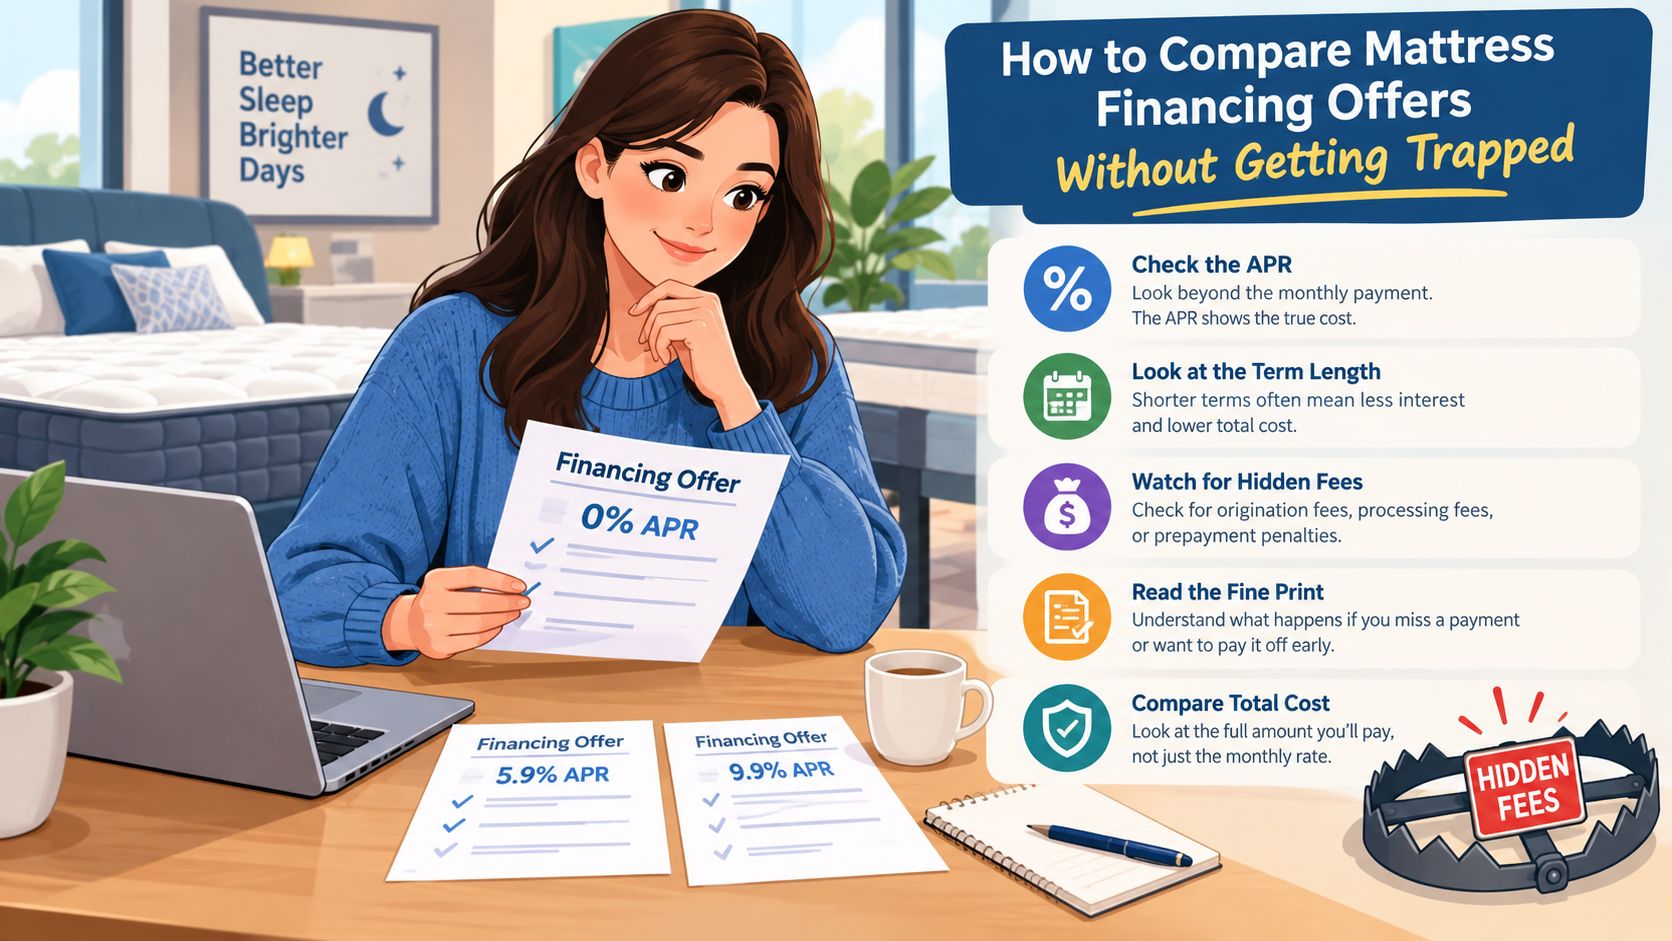
Two offers can show similar monthly payments while creating very different total costs. The key distinction is whether the plan uses true installment financing or deferred interest.
A true 0% installment plan states that interest isn't charged during the promotional term, subject to the agreement's conditions. A deferred-interest store-card promotion may also display 0% during the offer, but interest can be charged retroactively on the original purchase balance if the buyer doesn't pay in full by the deadline. The headline is similar. The risk is not.
Read the terms, not the banner
Third-party installment plans commonly advertise 0% to 36% APR over 3 to 60 months, while store-card promotions often use deferred interest with standard APRs around 29% to 34%, according to mattress financing offer guidance. Current store-card examples include variable purchase APRs of 33.74% and 34.99%, with one example listing a 39.99% penalty APR, as detailed by mattress financing payment-plan information.
Those rates matter because missing the payoff window can erase the benefit of the promotion. Some offers also require a minimum purchase amount, a deposit, equal monthly payments, or a particular payment schedule. Late fees can add another problem. Recent consumer guidance identifies late BNPL fees of roughly $5 to $25 per missed payment and post-promotion rates often in the 25% to 30% range, as explained in this mattress financing options guide.
Ask these questions before accepting
- Interest structure: Is the offer true 0% APR, or is interest deferred until the end?
- Payoff deadline: What exact date requires the balance to be paid in full?
- Total cost: What amount will be paid if every payment arrives on time?
- Missed deadline: Is interest applied to the remaining balance or the original purchase amount?
- Purchase conditions: Is there a minimum purchase, deposit, or required payment amount?
- Fees: Are there application, account, late, or promotional fees?
- After the promotion: What APR applies when the promotional period ends?
A shopper managing other balances may also benefit from reviewing a debt payoff method for credit cards before adding new credit. The point isn't to avoid every financing option. It's to avoid stacking obligations without a clear payoff order.
At Groen's, shoppers can ask the team to explain the available Special Financing terms and compare them with cash payment or other options. The furniture payment plan information can help buyers understand that financing structures differ, so the contract deserves careful attention.
Smarter Alternatives When Financing Is Not the Best Fit
Financing isn't the only way to make a mattress purchase manageable. A household with a mattress that still provides adequate support may choose to save gradually and buy without a credit obligation. That approach protects flexibility, but it doesn't make sense when the current mattress causes persistent discomfort or has clearly lost its function.
Layaway can suit shoppers who want to reserve a mattress while paying over time without taking on the same type of credit balance. The terms vary, so the buyer should confirm the deposit, payment schedule, cancellation rules, and delivery timing before committing. Waiting for a seasonal value event may also work when replacement isn't urgent, but delaying a necessary sleep purchase to chase a future promotion can carry its own cost in lost rest.
Match the option to the mattress's useful life
The Sleep Foundation's 6 to 8 year replacement benchmark provides a useful planning horizon, but mattress construction changes the expected service period. Industry guidance places budget innerspring mattresses around 5 to 7 years, mid-range hybrids around 7 to 10 years, memory foam around 8 to 10 years, and latex around 12 to 15 years, according to the Sleep Foundation's mattress information.
A short promotional term may fit a mattress expected to provide years of service. A long payment term deserves more scrutiny, particularly if payments could continue after the product has reached the end of its useful life. The buyer should finance the need, not stretch a temporary budget problem across an unnecessarily long obligation.
Plan larger home purchases with the same discipline
The same thinking applies to other furniture investments. A family planning a Canadel dining set can use the custom program to design it their way, while buyers choosing Amish solid wood furniture can plan around craftsmanship and specifications rather than rushing into a purchase. Groen's also offers Interior Design assistance and White-Glove Delivery for households coordinating a broader home update.
Shoppers who need a different payment approach can review furniture payment plans without a credit check and ask which conditions apply. Saving, layaway, cash, and financing each have a place. The best choice depends on urgency, durability, and the household's ability to keep the commitment comfortable.
Your Next Steps to Rest Easy With Groen's Fine Furniture
The decision becomes clearer when comfort and repayment are considered together. If the current mattress no longer supports restful sleep, a quality replacement can be a sensible wellness purchase. If the proposed payment would consume the household's margin, waiting or choosing a different payment path is the more responsible decision.
A showroom visit helps shoppers evaluate what payment math can't show. At Groen's Fine Furniture in Dyer or Crown Point, NWI families can test-drive Serta and Beautyrest mattresses, compare feel and support, and use the Helpful Mattress Guide to organize the decision around sleep needs rather than brand names alone.
The same family-owned team can explain Special Financing, subject to credit approval, without treating approval as proof that a purchase fits the budget. Shoppers can also explore Flexsteel durability, Bassett style, American-Made options, and Amish craftsmanship in solid wood furniture. Canadel custom dining remains available for buyers who want a made-to-order gathering place designed around their home.
Groen's serves Dyer, Crown Point, St. John, Schererville, Munster, and neighboring Northwest Indiana communities with multigenerational ownership and 5-star service. White-Glove Delivery and Interior Design support can carry the experience from choosing the right comfort to completing the room.
The next step is simple. Bring the household budget, ask for the full financing terms, and test the mattress in person. A clear payoff plan and comfortable support belong in the same decision.
Visit Groen's Fine Furniture in Dyer or Crown Point to test-drive Serta and Beautyrest mattresses, explore custom furniture options, and ask about Special Financing plans subject to credit approval. Let the Groen family help create a home with lasting comfort, honest value, and the personal 5-star service Northwest Indiana families deserve.